AI Disinflation Will Cut Mortgage Rates by Cutting Your Job First
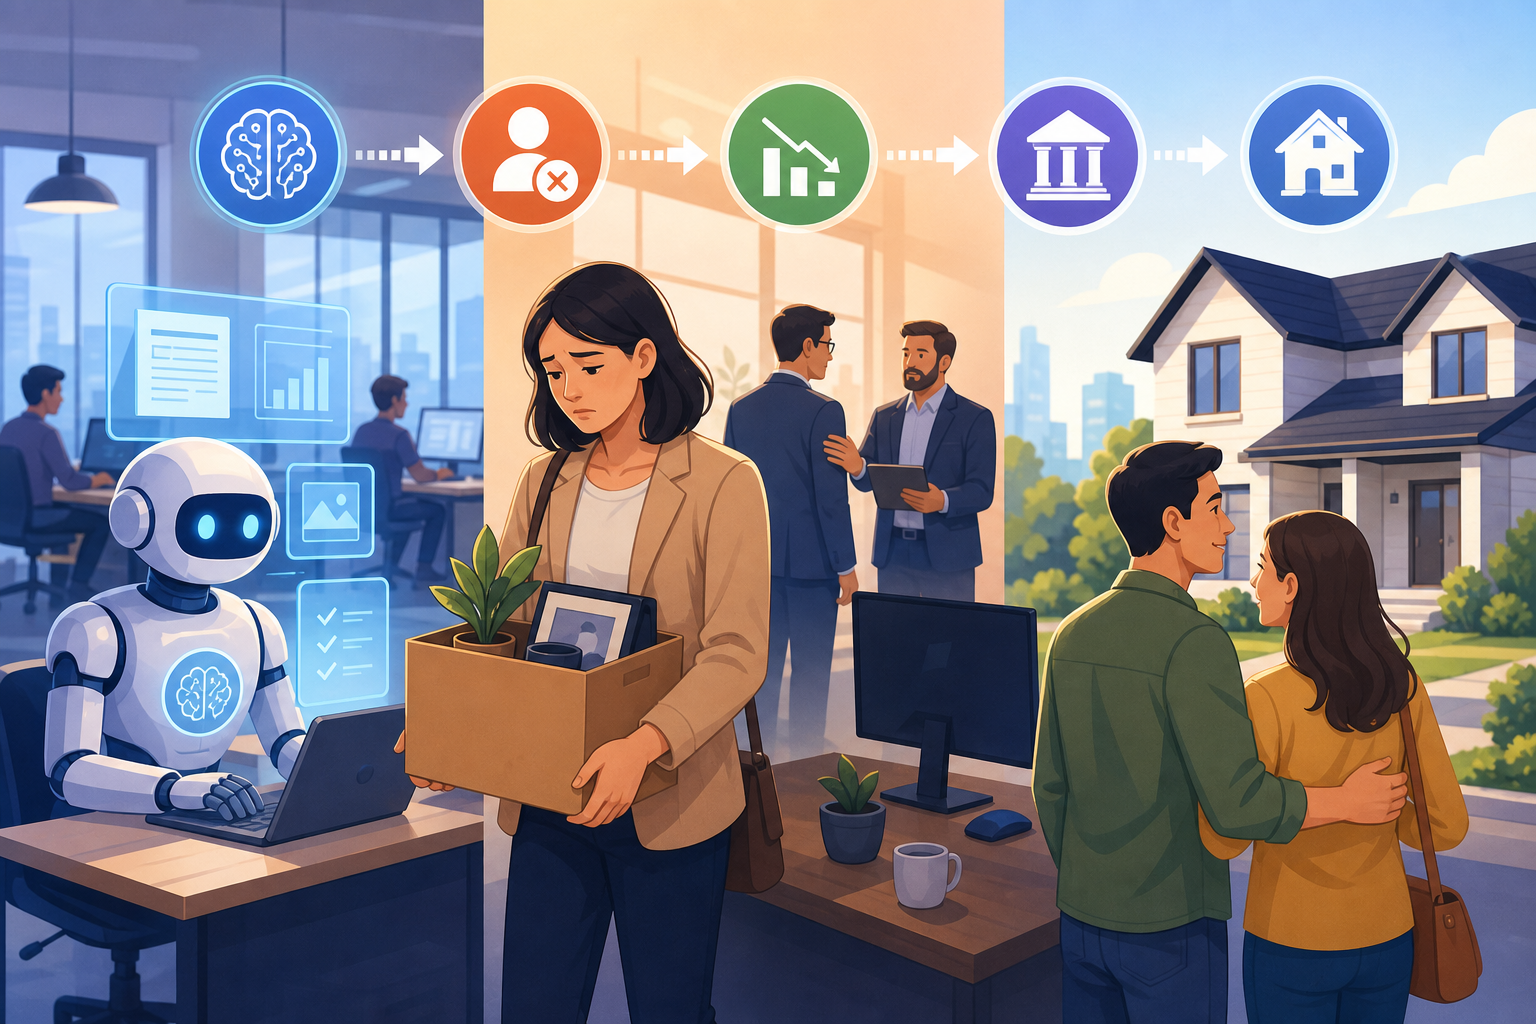
The Bank of Canada held its overnight rate at 2.25% this week while economists at RBC flagged something sharper than a typical policy call: AI productivity gains could suppress price growth enough to bring mortgage rates down within 18 months, but the channel running through jobs lost, not efficiency shared.
That sequencing matters. Disinflation driven by technology usually shows up first as head count reduction, then as lower business costs, and eventually as rate cuts once central banks confirm the inflation trend has shifted. The mortgage borrower waiting for a 4.5% five-year fixed in late 2027 may get it, but only after the machine-learning deployment that eliminated their marketing coordinator role in Q3 2026.
The Mechanism Behind AI Disinflation
RBC's analysis traces the path from generative AI adoption to falling consumer prices. Firms deploy models to replace mid-tier knowledge work. Payroll costs drop. Output per remaining employee rises. Competition forces firms to pass some of the savings to customers rather than holding margin. The weighted basket of goods and services the Bank of Canada watches starts to cool because the cost structure underneath shifted.
AI-driven workforce changes are already underway. Some Canadian customer service and call centre operations have begun replacing Tier 1 support with LLM-driven systems. The employees displaced have often moved to contract gig work or left the labour force. Unemployment in some regions has risen modestly even before the broader CPI impact has registered.
The mortgage rate response lags because central banks cut when the trend is durable and employment risk is material. A short-term productivity bump that raises margins gets no easing. A structural shift that raises unemployment and lowers wage growth does. AI delivers the second kind, which is why RBC sees rate cuts as an endgame that follows the job losses.
Who Loses Work Before Rates Fall
The jobs most exposed are the ones where output is text, where quality is hard to measure, and where the work does not require physical presence or licensed authority. Marketing copywriters, junior analysts, paralegal researchers, HR coordinators, first-line customer support. Not all at once. Attrition that doesn't get backfilled. Agencies that used to staff five people on an account now staff two and a subscription.
The paradox: these are also the households most likely to be stretching for a first home in Vancouver or Toronto. A 32-year-old content manager earning $68,000 in 2024 could afford a $520,000 condo with 10% down at a 5.2% rate. Two years later, the rate has dropped to 4.6%, but the job is gone and the new contract role pays $51,000 with no benefits. The qualification math moved the wrong direction even as the rate improved.
What the Timing Looks Like
If RBC's scenario holds, we see disinflation signals in service-sector CPI by mid-2027, enough for the Bank of Canada to restart cuts that stalled in early 2026. Five-year fixed rates, which peaked at 5.8% in late 2025, drift toward 4.7% by year-end 2027. Uninsured borrowers see the best improvement because the risk premium compresses when macro uncertainty falls.
But labour force participation has declined from 65.0% in January to 64.9% in February 2026, a trend that may continue if concentrated in the 25-to-40 demographic. First-time buyer mortgage originations may fall despite lower rates because fewer households can clear the stress test at any income level if this pattern holds.
The rate cut comes. It just comes for the buyers who kept their jobs.




The Bank of Canada held its overnight rate at 2.25% this week while economists at RBC flagged something sharper than a typical policy call: AI productivity gains could suppress price growth enough to bring mortgage rates down within 18 months, but the channel running through jobs lost, not efficiency shared.
That sequencing matters. Disinflation driven by technology usually shows up first as head count reduction, then as lower business costs, and eventually as rate cuts once central banks confirm the inflation trend has shifted. The mortgage borrower waiting for a 4.5% five-year fixed in late 2027 may get it, but only after the machine-learning deployment that eliminated their marketing coordinator role in Q3 2026.
The Mechanism Behind AI Disinflation
RBC's analysis traces the path from generative AI adoption to falling consumer prices. Firms deploy models to replace mid-tier knowledge work. Payroll costs drop. Output per remaining employee rises. Competition forces firms to pass some of the savings to customers rather than holding margin. The weighted basket of goods and services the Bank of Canada watches starts to cool because the cost structure underneath shifted.
AI-driven workforce changes are already underway. Some Canadian customer service and call centre operations have begun replacing Tier 1 support with LLM-driven systems. The employees displaced have often moved to contract gig work or left the labour force. Unemployment in some regions has risen modestly even before the broader CPI impact has registered.
The mortgage rate response lags because central banks cut when the trend is durable and employment risk is material. A short-term productivity bump that raises margins gets no easing. A structural shift that raises unemployment and lowers wage growth does. AI delivers the second kind, which is why RBC sees rate cuts as an endgame that follows the job losses.
Who Loses Work Before Rates Fall
The jobs most exposed are the ones where output is text, where quality is hard to measure, and where the work does not require physical presence or licensed authority. Marketing copywriters, junior analysts, paralegal researchers, HR coordinators, first-line customer support. Not all at once. Attrition that doesn't get backfilled. Agencies that used to staff five people on an account now staff two and a subscription.
The paradox: these are also the households most likely to be stretching for a first home in Vancouver or Toronto. A 32-year-old content manager earning $68,000 in 2024 could afford a $520,000 condo with 10% down at a 5.2% rate. Two years later, the rate has dropped to 4.6%, but the job is gone and the new contract role pays $51,000 with no benefits. The qualification math moved the wrong direction even as the rate improved.
What the Timing Looks Like
If RBC's scenario holds, we see disinflation signals in service-sector CPI by mid-2027, enough for the Bank of Canada to restart cuts that stalled in early 2026. Five-year fixed rates, which peaked at 5.8% in late 2025, drift toward 4.7% by year-end 2027. Uninsured borrowers see the best improvement because the risk premium compresses when macro uncertainty falls.
But labour force participation has declined from 65.0% in January to 64.9% in February 2026, a trend that may continue if concentrated in the 25-to-40 demographic. First-time buyer mortgage originations may fall despite lower rates because fewer households can clear the stress test at any income level if this pattern holds.
The rate cut comes. It just comes for the buyers who kept their jobs.
Sources
Read Next
Home Prices in 2027 Hinge on a Handoff From Population to Business Investment
Bank Rate Hikes Lift Your Qualifying Rate: 3 Moves on Term and Rate Shopping
Steady Policy Rate, Rising Fixed Rates: Reading the Gap Before You Lock In
The 39% Limit: How the Stress Test Sets Your Real Buying Power